Step 1: Find the Fit
A school that fits
the whole student.
Bring academic interests, campus life, and financial fit into the same conversation.
You can send your child to the college they deserve and not sacrifice your financial future.
Schedule a conversationGrants and scholarships will lower the tuition price. We find the schools that offer the largest discounts.
See the award lettersAverage annual tuition & fees · 1980–81 to 2025–26
Current dollars, not adjusted for inflation. Tuition and fees only; housing, food and other expenses are extra. *Estimated 2025–26 net averages for first-time full-time students. Your price and aid will vary.
Source: College Board, 2025 · View chart data
Step 1: Find the Fit
Bring academic interests, campus life, and financial fit into the same conversation.
Step 2: Understand the Aid
Navigate financial aid forms and compare offers with a clear view of grants, scholarships, and loans.
Step 3: Build the Plan
Consider the resources available to your family alongside cash flow, other children, and retirement.
A little clarity changes the picture.
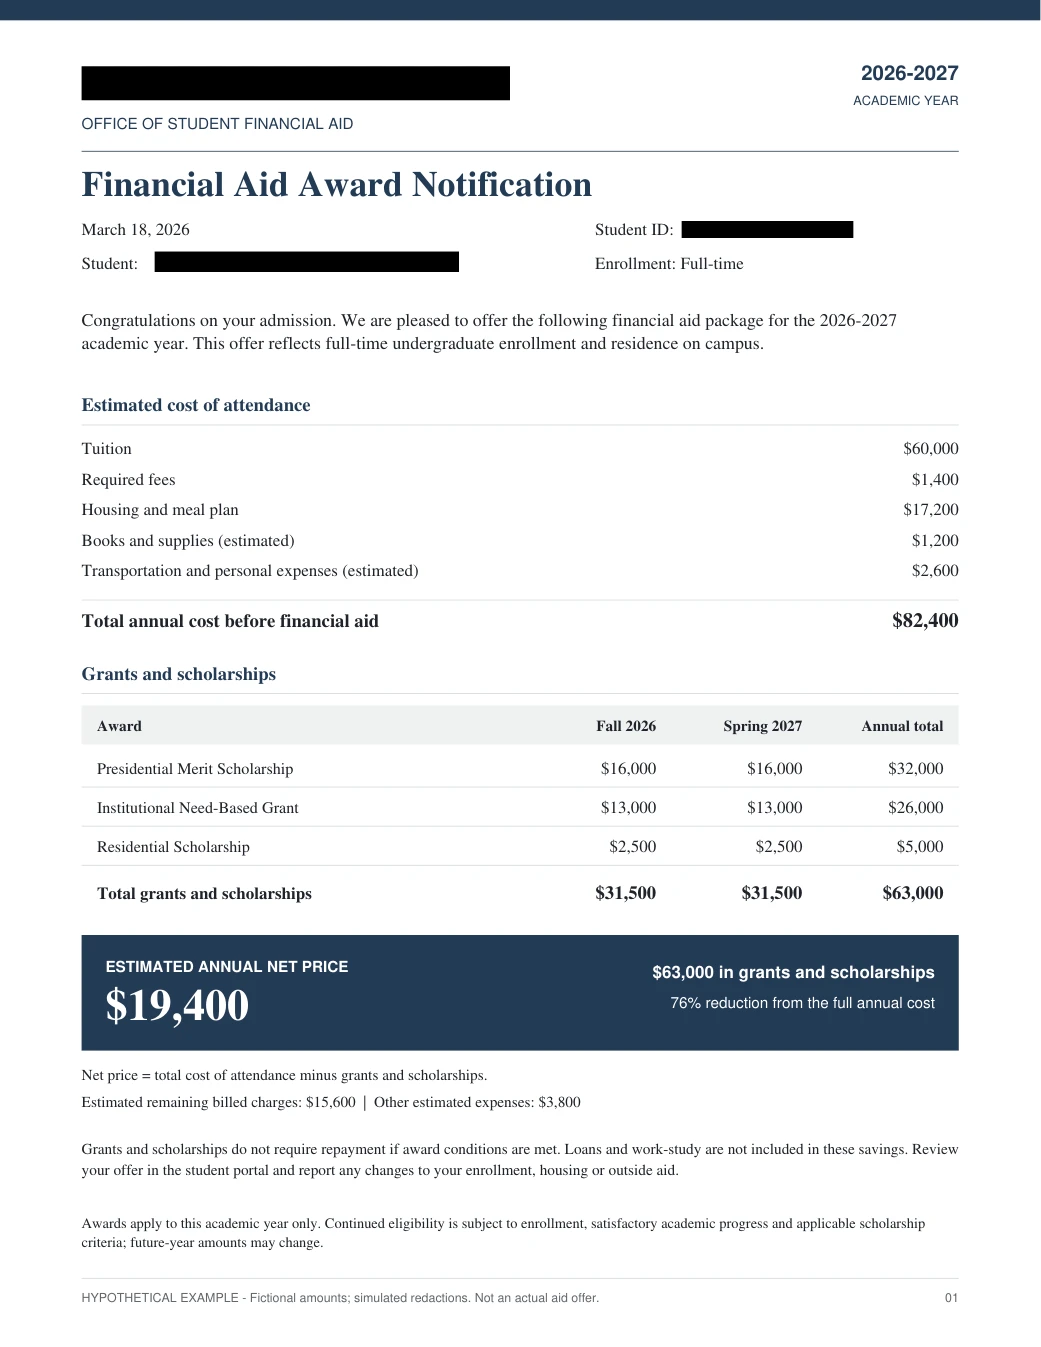
Three award letters. See how grants
and scholarships change the picture.
This example starts at $82,400 for one academic year, including tuition, fees, housing, books, and other estimated expenses.
Hypothetical 2026–27 example. Fictional amounts and simulated redactions. Not an actual offer, client result, or promise of aid. Future-year awards may change.
Borrowing helps pay a cost. It doesn’t reduce the cost.
How Federal Student Aid compares offers ↗From an offer to a plan.
Knowing the cost is a starting point. Together, we turn the numbers into a plan for your family, one decision at a time.
A hypothetical plan for a family with two students. Figures are educational assumptions, not a client result, recommendation, or guarantee.
Schedule a conversation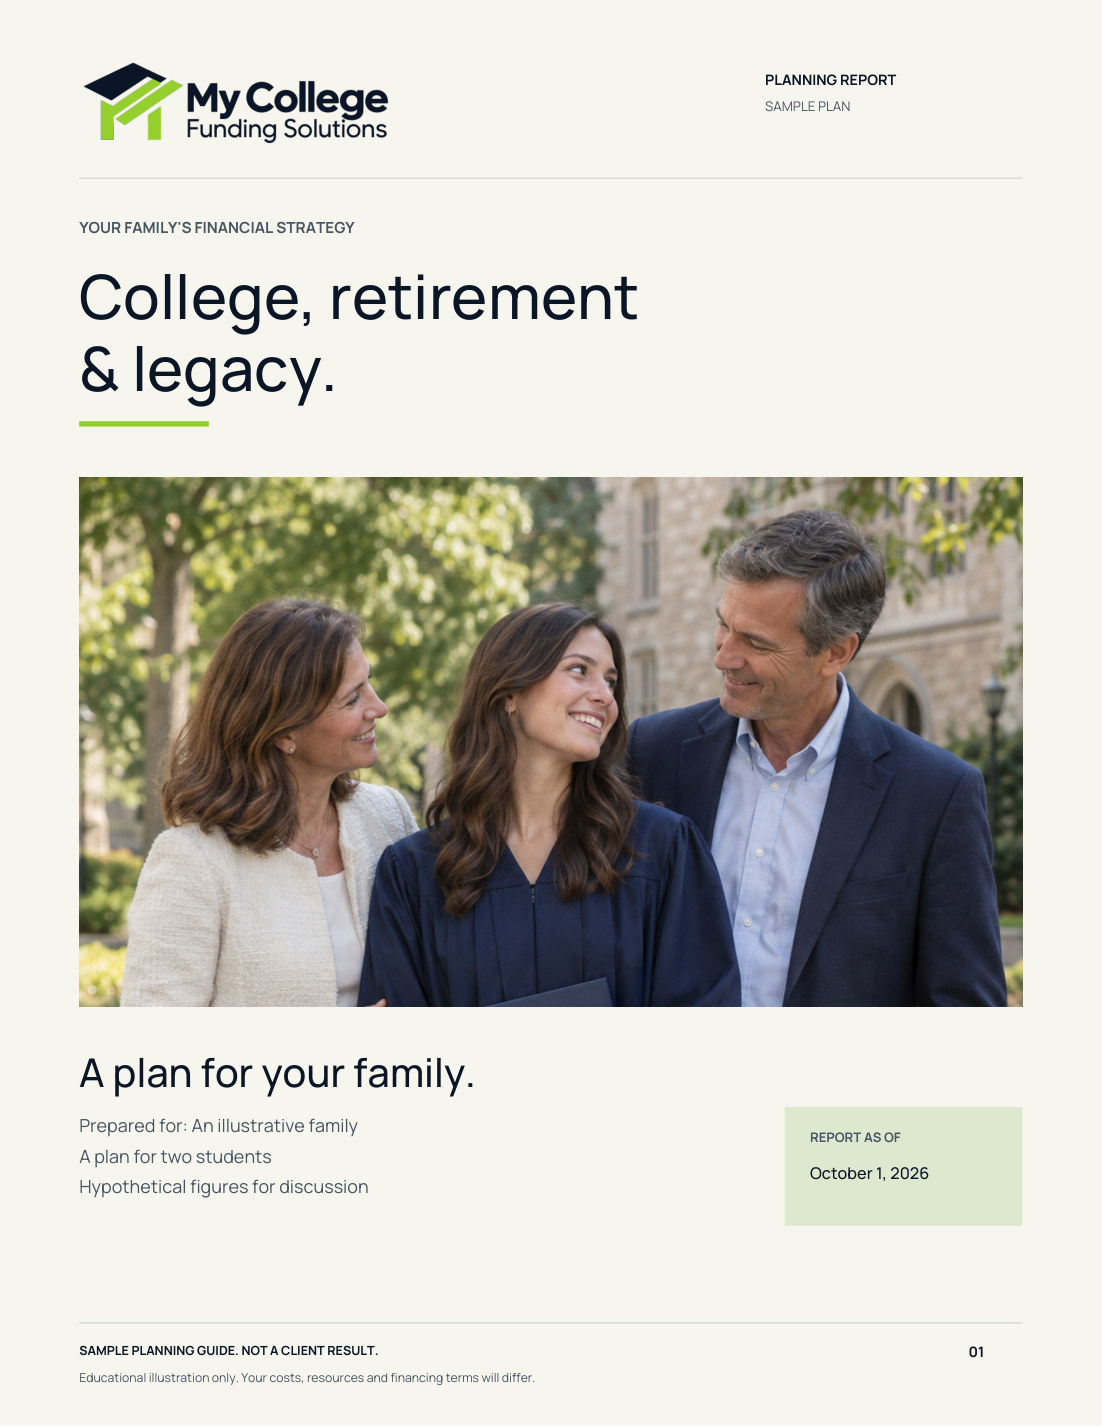
Your children’s college plans. Your resources. Your goals for what comes next. We start by understanding how they fit together.
Explore this page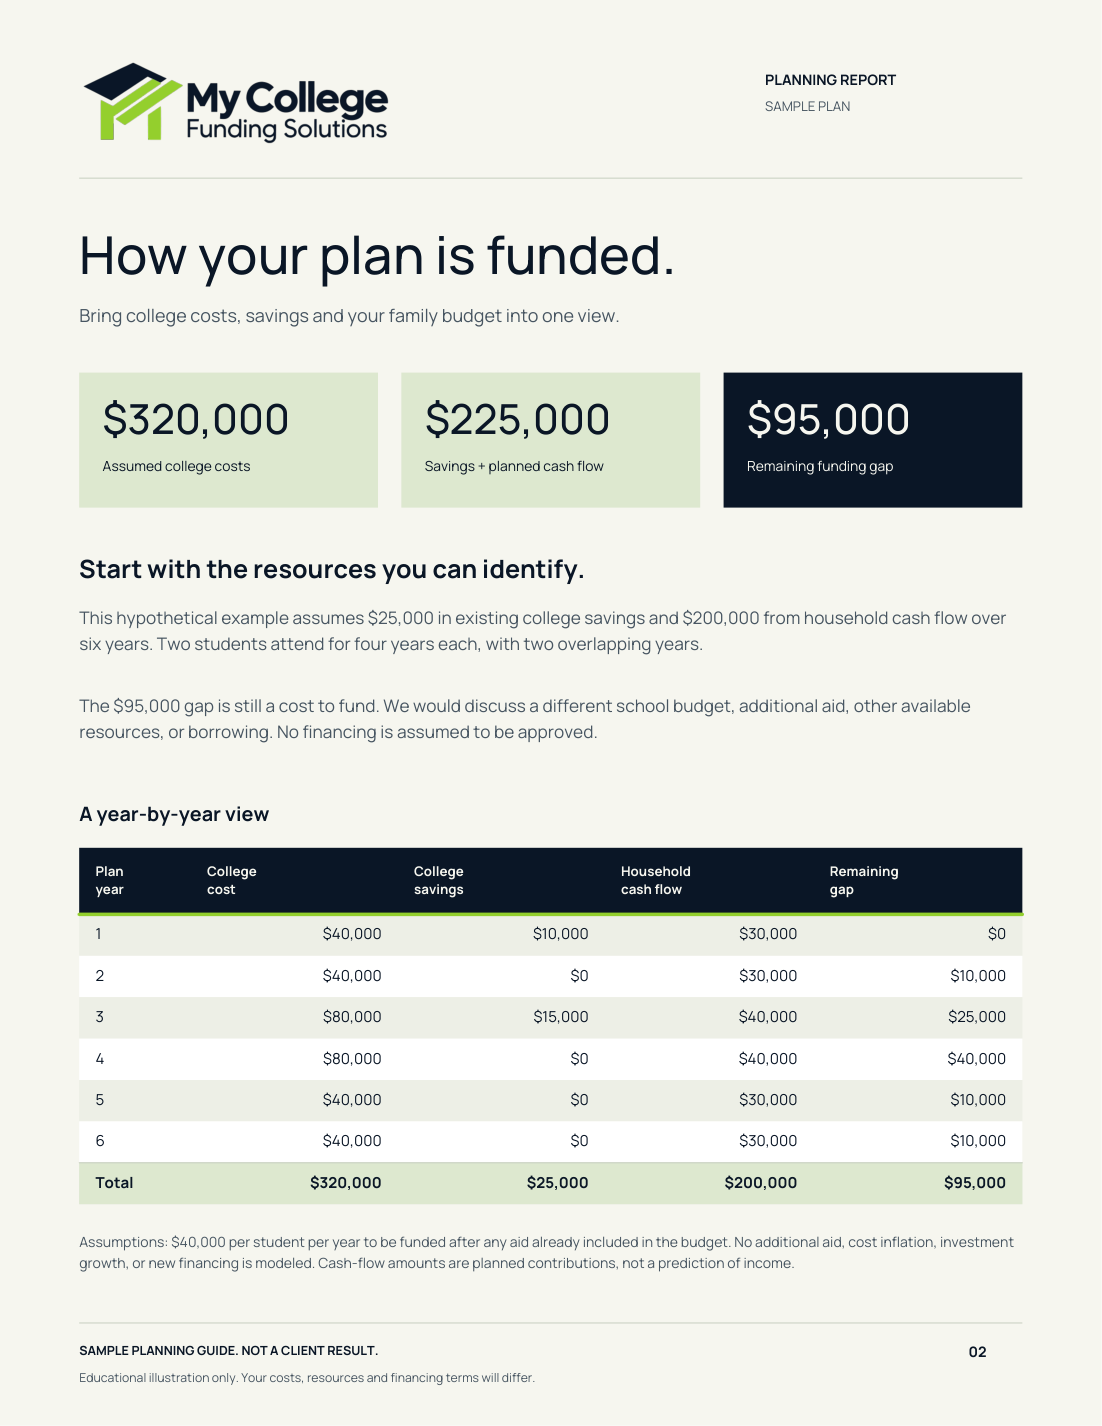
Lay out the expected costs and the resources available to cover them. See what comes from savings, ongoing cash flow, and any borrowing you are considering.
This example identifies a $95,000 funding gap to address through school choices, additional aid, family resources, or borrowing.
Explore this page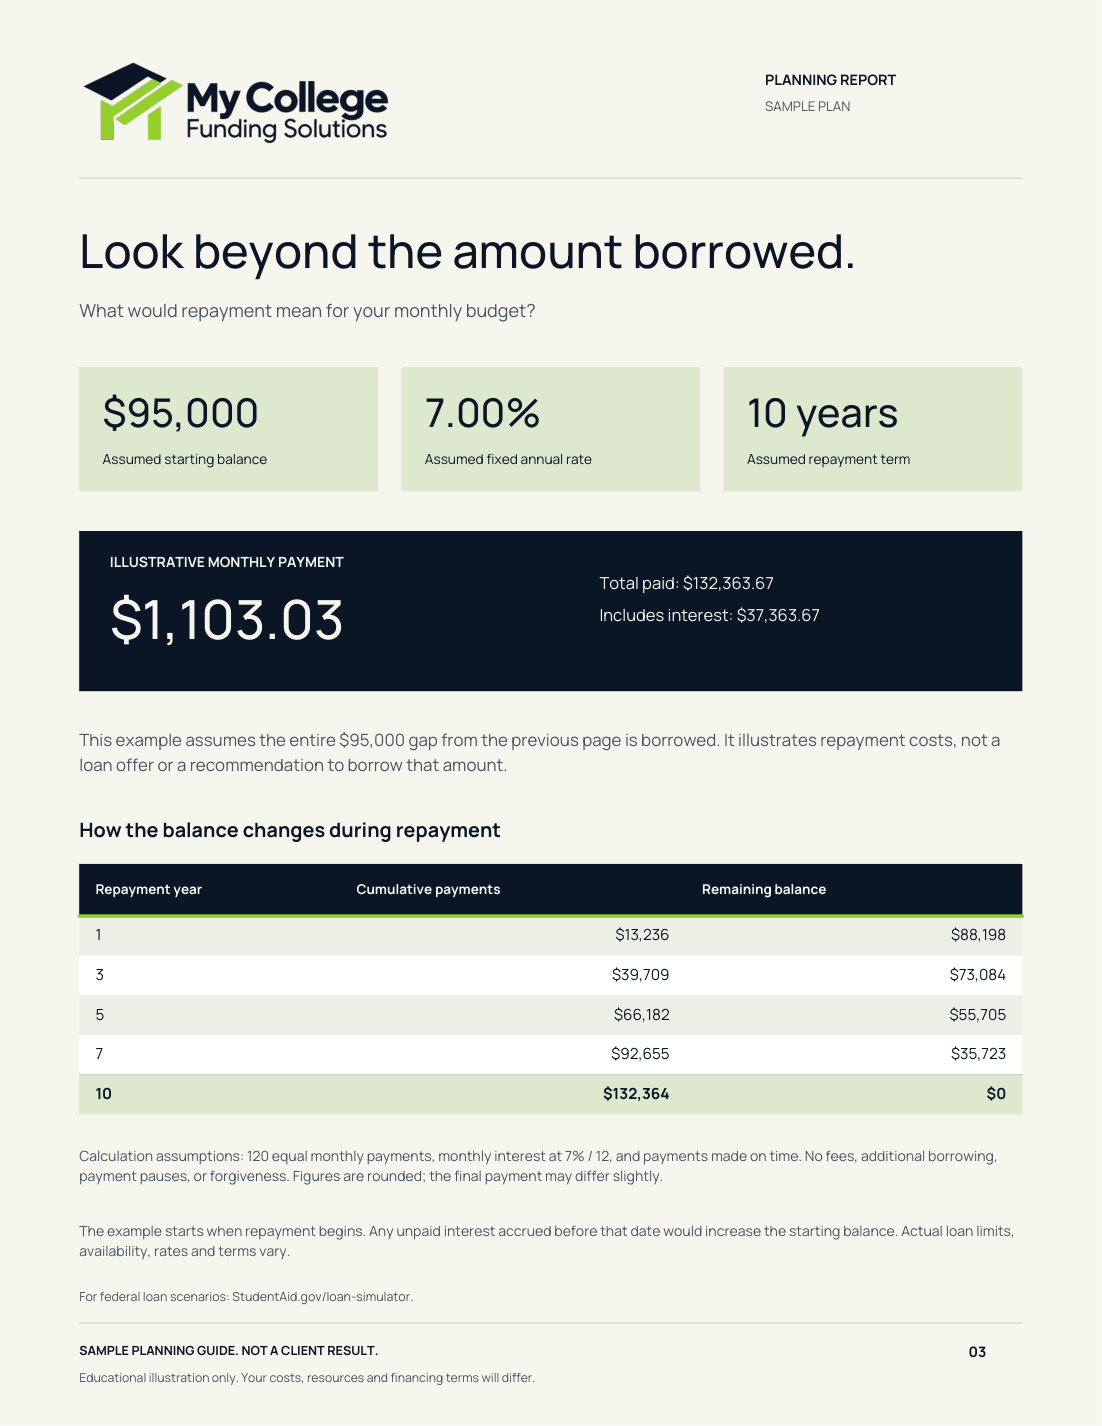
Bring the college years and the repayment years into the same view. We walk through the timing, assumptions, and tradeoffs with you.
This hypothetical loan example shows how interest and repayment timing affect the total cost. It is not a loan offer; actual terms and borrowing limits vary.
Explore this page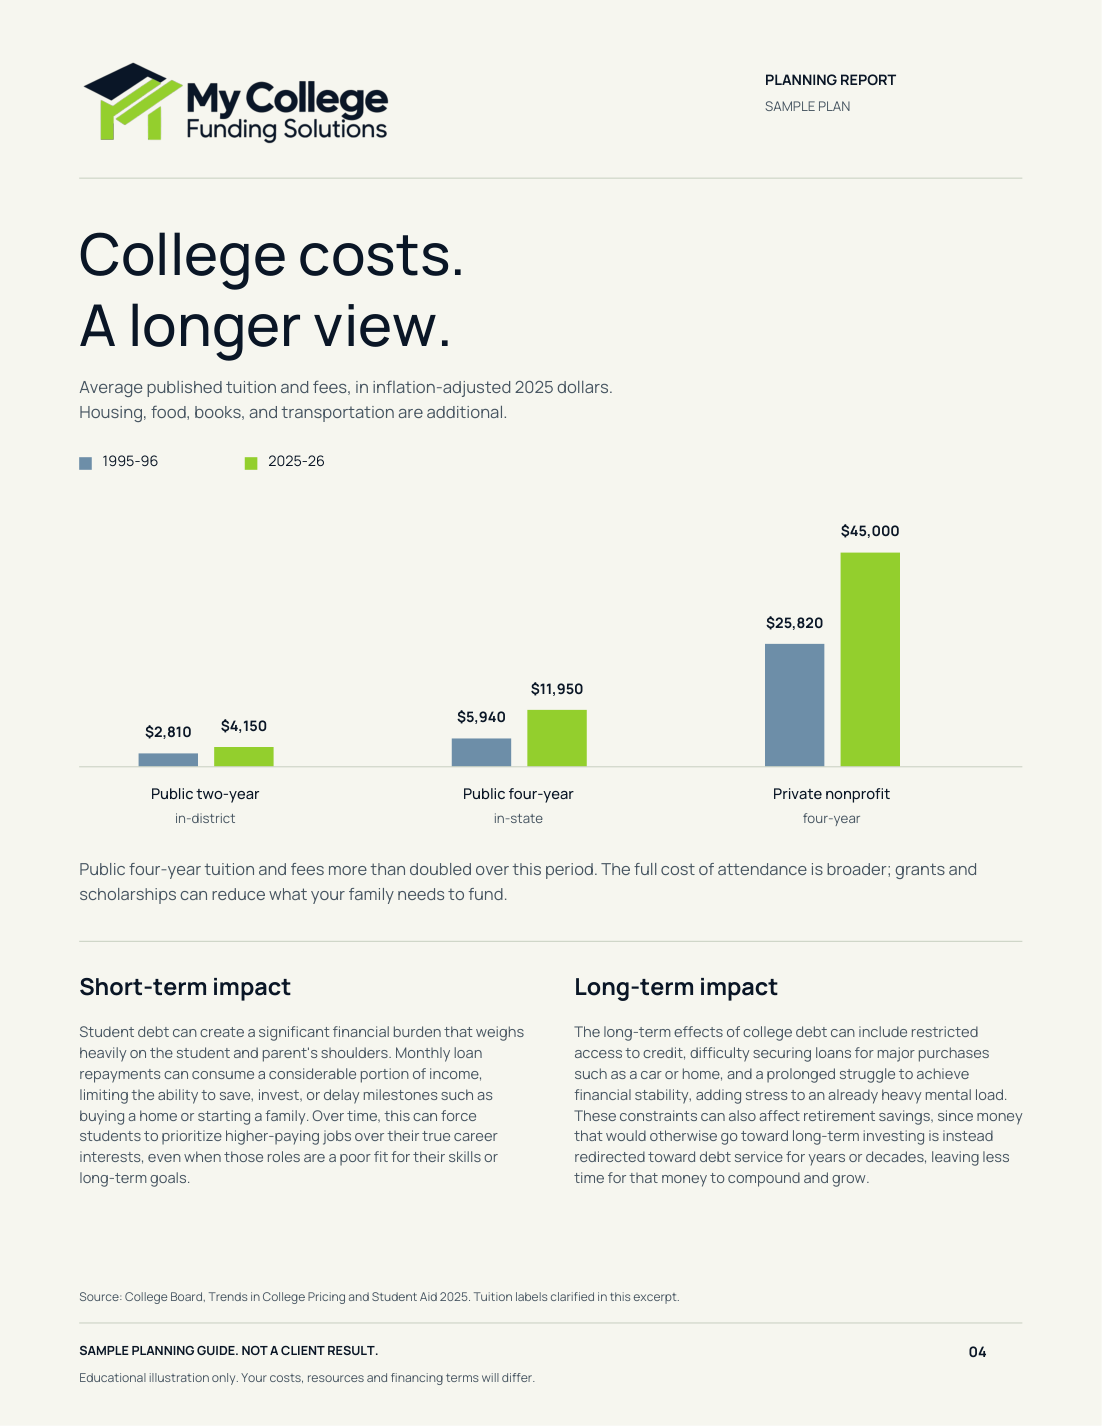
A funding choice can reach beyond graduation. We consider what the plan means for your family’s cash flow, other children, and retirement.
Historical tuition and fee data from College Board’s 2025 report.
Explore this pageAt age 75, that same $150,000 could have become $643,781. Spending them on college means giving up that potential retirement value in this example.
$150,000 today · 6% assumed annual return
Hypothetical growth, not a forecast. Future dollars before taxes, fees and inflation.
How this example works. All $150,000 is treated as paid today at age 50, rather than spread across college years. The alternative assumes it stays invested to age 75 at a constant 6%, compounded annually, with no additions or withdrawals. Actual returns vary and can be negative. This shows the investment tradeoff, not the full value of a college education.
Why age 50? It is an illustrative starting age. A 2013 U.S. study of 264 college-parent pairs reported a mean parent age of 50.93. That single-university sample is not a current national average. View the year-by-year calculation.
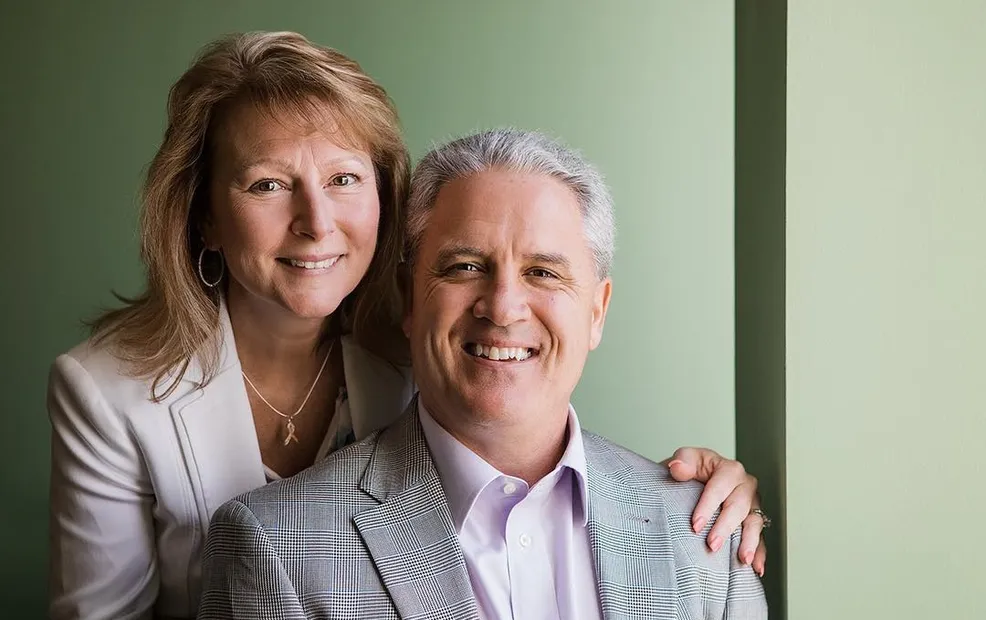
Real people. Personal guidance.
College planning comes with plenty of questions. You deserve someone who listens, explains your options, and helps you find a way forward.
Joe brings a background in engineering and business to college funding. Jo-Ann brings experience in credit and finance. Together, they help families make sense of the decisions ahead.
“We will listen to you carefully, so we can show you all the available options.”
Our pledge to parents
Get to know MacMunn FinancialSome families need help finding the right college. Others need support with the forms, the offers, or the whole journey.
Strategic planning is included in every plan.
We help you explore ways to pay for college while considering your lifestyle and retirement savings.
The Student Positioning Service focuses on the college search and admissions side for college-bound high school students and their parent(s).
The Forms & Awards Service focuses on the financial aid forms and awards side for college-bound high school students and their parent(s).
The Concierge program is an all-inclusive product for college-bound high school students and their parent(s). It is a combination of the Student Positioning plan and the Form and Awards plan.
The Concierge PLUS program is an all-inclusive product for college-bound high school students and their parent(s).
Additional services include:
Hear more about connecting college planning with your family’s financial future, in your own time.
Watch the college-planning seminar Open the introduction on YouTube ↗Previously recorded educational videos. Discuss current rules and your circumstances with us.Practice identifying grants, loans, and work-study in a different format.
View the ABC University sample ↗Your family. Your questions. A place to begin.
Tell us where you are in the college journey.
We’ll start there.
Educational information only. Financial aid eligibility, awards, and costs vary by student and institution. Examples include hypothetical awards with fictional amounts and simulated redactions, not actual aid offers, client results, or guarantees.
Joseph MacMunn is a financial advisor of LifePro Asset Management, LLC. Investment advisory services offered through LifePro Asset Management, LLC, a registered investment adviser. MacMunn Financial Management, Inc. is neither an affiliate nor a subsidiary of LPAM.
Advisory services are only offered to clients or prospective clients where LifePro Asset Management, LLC and its representatives are properly licensed or exempted. Different investments involve varying degrees of risk. No assurance can be given that an investment or strategy will be profitable.
Customer Relationship Summary (Form CRS) ↗ · Registration information (CRD #285252) ↗
The external booking, video, and social services linked here have their own privacy practices.